
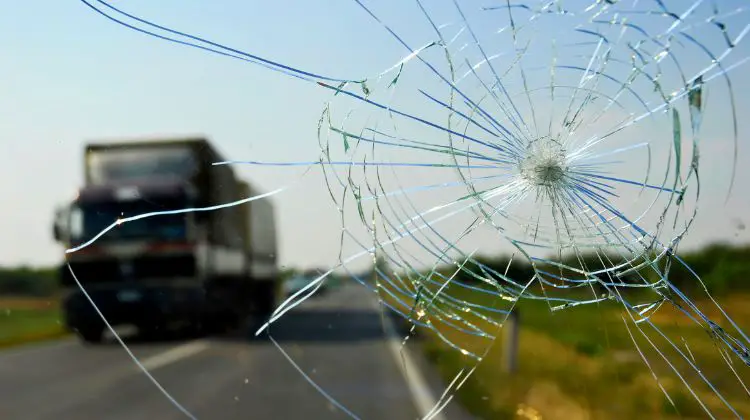
You’re driving down the highway, minding your own business, when you hear it. It’s that loud, gut-wrenching smack of a rock hitting your windshield. A tiny chip quickly becomes a sprawling crack, and now you have a big problem with a damaged windshield.
You immediately start thinking about the cost of getting the windshield fixed. Your mind jumps to your insurance policy, and you wonder, does car insurance cover windshield replacement? It’s a frustrating spot to be in, and the answer isn’t always a simple yes or no.
Whether your auto insurance will handle the bill depends entirely on the type of insurance coverage you have. Understanding your policy can feel overwhelming, but you’ll learn exactly what to look for and what questions to ask. Knowing if your specific policy provides for car insurance cover windshield replacement is the first step to getting your car fixed without a financial headache.
Table of Contents:
- What Type of Insurance Actually Pays for Windshield Damage?
- The Big Question: What About the Deductible?
- Should You Repair or Replace Your Windshield?
- Filing a Claim for Car Insurance Cover Windshield Replacement
- Will Filing a Windshield Claim Raise My Rates?
- Paying Out-of-Pocket: When It Makes Sense
- Conclusion
What Type of Insurance Actually Pays for Windshield Damage?
If you’re like most people, you bought the vehicle insurance you were legally required to get and maybe a little extra. But you might not know what each part of your policy does. Not all car insurance policies are created equal, especially when it concerns glass damage.
Simply having the state minimum liability coverage probably won’t help you here. That type of insurance pays for damage you cause to other people’s property, not your own car. So, if your windshield gets cracked by a random rock, your basic liability policy won’t do a thing for your broken windshield.
For your own vehicle’s glass to be covered, you generally need more than just the basics. You need what’s often called “full coverage,” which usually means you have both comprehensive and collision insurance. These two coverages are what will protect you in this situation, but it’s important to understand how they differ.
The Role of Comprehensive Coverage
This is the part of your insurance policy you’ll most likely be using for windshield glass damage. Comprehensive coverage helps pay for damage to your car from things other than a car accident. Think of it as your protection against unexpected and unpredictable events that are out of your control.
Events like a rock kicked up from the road, a hailstorm that leaves pits and cracks, or a tree branch falling on your parked car are all typically handled by comprehensive insurance. It also covers vandalism if someone intentionally damages your windshield. This is your go-to coverage for most glass-only replacement claims.
If you have this coverage, you’re in a good position to get help paying for the repair or replacement. This is usually the specific part of a policy that covers windshield replacement when there isn’t another car involved. It’s a vital part of a robust auto insurance plan.
How Collision Coverage Fits In
Collision coverage is different from comprehensive. It pays to fix your car when you’re in an accident with another object, whether it’s another vehicle or something stationary like a guardrail or a telephone pole. You might be wondering how this relates to your windshield.
If your windshield is damaged as part of a larger accident that you caused, this is where collision coverage would step in. For example, if you rear-end someone and your windshield shatters, the replacement would be part of the overall collision claim. The claim would cover all property insurance aspects of the incident, from bumpers to glass.
The entire claim would be handled under one single collision incident. It would cover the bodywork, mechanical repairs, and the windshield glass all at once, subject to your collision deductible. This differs from isolated glass damage where only your comprehensive insurance would apply.
When Another Driver’s Liability Pays
There’s one other scenario where you won’t need to use your own coverage. If another driver is clearly at fault for an accident that damages your windshield, their insurance should pay for it. Their property damage liability coverage is meant to fix your car.
For this to work, the other driver must be identified and found legally responsible for the accident. This applies to a car crash, not a rock flying up from a dump truck, which is almost impossible to prove fault for. But in a clear-cut accident, you shouldn’t have to pay a dime out of your own pocket to have your glass repaired.
You would file a claim against their policy, and their insurer would manage the repairs. This way, you avoid paying your own car insurance deductible. It also keeps the claim off your personal insurance history, which can be beneficial in the long run.
The Big Question: What About the Deductible?
Even if you have the right coverage, you probably won’t get a completely free ride. That’s because of the insurance deductible. It’s the amount of money you have to pay out-of-pocket for a claim before your insurance company starts to pay.
Most comprehensive and collision coverages come with a deductible, which can range from $100 to over $1,000. For example, if your windshield replacement costs $600 and your comprehensive deductible is $500, you pay the first $500. Your insurance would then cover the remaining $100.
Because of this, you should always check the repair cost first. If a glass service quotes you $450 to replace the glass and your deductible is $500, it makes no sense to file a claim. You’d just be better off paying for it yourself to avoid a needless claim report.
Full Glass Coverage: The No-Deductible Option
Some insurance companies offer an excellent add-on to your policy called full glass coverage or a zero-deductible glass option. It’s an optional feature you can add to your comprehensive plan. Many drivers consider it a form of specialized windshield insurance.
With this add-on, you typically pay a little more on your premium. In return, the insurer will waive your deductible for any windshield glass repairs or replacement. That means if a rock causes a cracked windshield, you can get it fixed for $0 out-of-pocket.
This is a fantastic deductible option if you live in an area with a lot of road construction or just want peace of mind. Not all companies offer it, and it isn’t available in every state, so you’ll have to ask your insurance agent if it’s something you can add. It is separate from other perks like roadside assistance or phone protection.
Special State Laws You Should Know
Insurance is regulated at the state level, and a few states have specific laws about windshields. According to the Insurance Journal, states like Florida, Kentucky, and South Carolina are known as “zero deductible” states. This can be a huge benefit for drivers living there.
In these states, if you have comprehensive coverage, your insurance company is legally required to waive the deductible for windshield repairs or replacements. It’s part of the law, aiming to keep drivers safe without a financial barrier to clear vision. Drivers in these states can often get a new windshield without paying anything, which encourages them to get a damaged windshield fixed promptly.
It’s always a good idea to know your local state laws, because you might have benefits you’re not even aware of. A quick check of your state’s department of insurance website or a review of your policy documents can give you this information. Your insurance card might also have a specific number to call to report glass damage.
Should You Repair or Replace Your Windshield?
Once you see damage, you have to decide whether you need a simple repair or a full replacement. A general rule of thumb used by professionals is the “dollar bill” test. If the chip or crack can be completely covered by a dollar bill, it can likely be repaired.
A repair involves injecting a special resin into the chip, which hardens and prevents the crack from spreading. This process is much cheaper and faster than a full replacement. Many insurance companies will even waive your deductible for a repair because they’d rather pay for a small fix now than for a larger replacement later.
But if the crack is longer than about six inches or directly in the driver’s line of sight, a full replacement is usually necessary for safety. Your windshield is a critical component of your vehicle’s structural support, so you should not put off getting it fixed. A small crack can quickly become a crack larger than a dollar bill with temperature changes or road vibrations.
| Factor | Windshield Repair | Windshield Replacement |
|---|---|---|
| Damage Size | Generally for chips or cracks smaller than a dollar bill (or 6 inches long). | For larger cracks, multiple cracks, or damage in the driver’s direct line of sight. |
| Cost | Much lower, often under $150. Many insurers waive the deductible. | Higher, from a few hundred to over $1,500 for cars with ADAS technology. |
| Time | Quick, usually completed in under an hour. | Takes longer, from one to several hours, plus potential recalibration time. |
| Insurance Impact | Often has a waived deductible and is less likely to affect premiums. | A claim is subject to your comprehensive deductible. |
| Safety | Restores strength and prevents spreading. The original factory seal remains intact. | Restores full structural integrity and safety. Critical for extensive damage. |
Filing a Claim for Car Insurance Cover Windshield Replacement
If you’ve decided to file an auto glass claim, the process is usually straightforward. Insurance companies handle replacement claims all the time, so they’ve made it pretty easy. Here’s a simple path to follow to get your windshield repaired or replaced.
First, document the damage. Take clear photos of the chip or crack from both inside and outside the car. It’s also helpful to measure it so you can give the insurance company precise information for the claim report.
Next, contact a reputable auto glass shop to get an estimate. Finding out the cost to get your windshield fixed is vital for deciding if a claim is worth it compared to your car insurance deductible. Some shops specialize in glass-only replacement and work directly with insurers.
If you decide to proceed, contact your insurance company. You can usually report glass claims online, through a mobile app, or by calling your agent. They will guide you through the next steps, which often involves them connecting you with one of their approved glass service partners.
Will Filing a Windshield Claim Raise My Rates?
This is the question that stops many people from filing a claim. You don’t want a small fix today to lead to higher bills for years to come. Generally, a single comprehensive claim for a windshield is not likely to increase your premium directly.
The main question is how will the claim affect your rates. Insurance companies tend to be more lenient with comprehensive claims than with collision claims because they are not related to your driving habits. A rock hitting your glass is seen as bad luck, not bad driving, so one of these replacement claims usually won’t hurt you.
However, the most common issue is losing a “claims-free” discount. Many insurers offer this for going a certain number of years without filing any claims. A windshield claim, no matter how small, could make you lose that discount, which will feel just like a rate increase on your next bill.
Paying Out-of-Pocket: When It Makes Sense
Sometimes, the smartest financial move is to leave your insurance out of it. There are several good reasons to pay for a new windshield yourself. It all comes down to doing a little math and thinking long-term about your insurance policy.
The most obvious reason is when your deductible is higher than the replacement cost. If the bill from the glass repair shop is $400 and your deductible is $500, the choice is simple. You would save $100 just by paying the shop directly and avoiding an auto glass claim.
You also might choose to pay yourself to protect your claims history. Even if it doesn’t raise your rates, a claim will be on your record for several years. Having a clean record can be valuable if you shop to quote car insurance later or if you have a more serious claim, such as a total loss, in the future.
Finally, consider the technology in your car. Newer cars with Advanced Driver Assistance Systems (ADAS) have sensors and cameras mounted in the windshield glass. Replacing this glass can cost upwards of $1,000 because these systems need professional recalibration, a process that ensures features like automatic braking and lane assist work correctly. In these expensive cases, using your insurance makes much more sense.
This consideration is different for business owners with a commercial auto policy. Their business insurance might have different terms for glass repairs and replacements. It’s wise for them to check their specific policy details.
Conclusion
Figuring out if your car insurance cover windshield replacement doesn’t have to be a major headache. For most drivers with comprehensive coverage, the answer is yes, you’re likely protected from those surprise damages. But you must be mindful of your insurance deductible and how it compares to the cost of the fix.
It is always smart to understand your own insurance policy before you need it. By knowing if you have comprehensive coverage, what your deductible is, and whether you have a zero-deductible deductible option, you can make a clear-headed decision when damage happens. Ultimately, a little knowledge empowers you to handle the situation correctly and get back on the road safely.
At the end of the day, knowing the specifics of how your auto insurance covers windshield replacement under your own plan gives you control. You can weigh the pros and cons of filing a claim versus paying yourself. This puts you in the driver’s seat of your finances, even when life throws a rock your way.




Reader Interactions